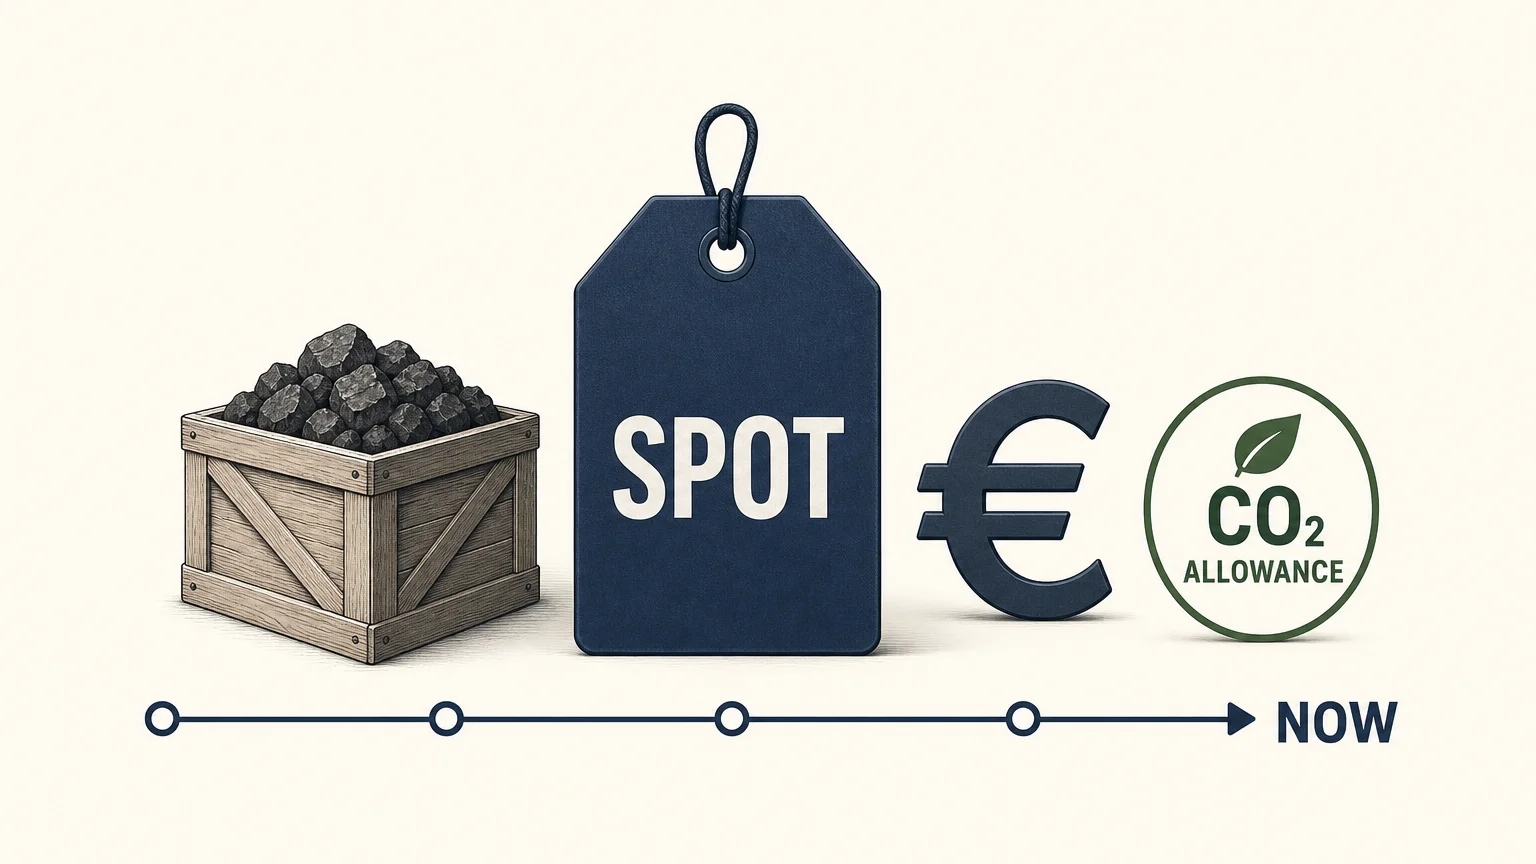
When you search for the definition of spot price, the central question is simple: what would an asset cost if you bought it for delivery now? For a practical comparison of immediate and later delivery in EU carbon markets, see our EUA futures vs EUA spot guide.
The spot price is also called the cash price. It reflects the market value of a specific asset, quantity, location, and delivery arrangement at a given moment. The EIA glossary defines it as a price for a one-time open market transaction involving near-term delivery at current market rates.
What is the definition of spot price?
A spot price is the price at which an asset can be bought or sold for immediate or near-term delivery and settlement. The asset may be a commodity, currency, security, energy product, or emissions allowance. The exact meaning of “immediate” depends on the market’s normal settlement convention.
For example, a spot transaction in foreign exchange may settle within a standard banking period. A physical commodity transaction may require transportation before the buyer receives the goods. An EU Allowance transaction may involve electronic transfer through the relevant market and custody arrangements rather than physical shipment.
The important point is that the transaction concerns the asset’s value now, not a price fixed exclusively for a future delivery date. The spot price therefore provides a reference for the underlying asset before additional costs, contractual adjustments, or product premiums are added.
Spot prices are not universal numbers for every possible transaction. They can vary by asset quality, delivery location, quantity, currency, settlement terms, and market liquidity. A widely quoted benchmark may represent a standard grade or contract, while a particular buyer receives a different executable quote.
Does immediate delivery mean instant delivery?
The word “spot” does not always mean that payment and delivery happen in the same second. It means the transaction is intended for the market’s current or near-term delivery window, rather than a distant date.
Delivery conventions differ across markets. A currency trade may settle through financial accounts. A crude oil transaction may involve a specified port, grade, and loading period. A metals transaction may refer to approved warehouses, while a carbon allowance transaction may involve electronic custody and settlement.
Location matters because transportation and regional availability affect the price. A barrel of oil available at one trading hub may not have the same value as a barrel available elsewhere. The same principle applies to electricity, natural gas, agricultural products, and other assets that cannot be moved without cost.
Quantity also matters. A large institutional order may receive a different price from a small order because the trade can affect available liquidity. A quoted spot price can therefore be a benchmark, a bid, an offer, or an executable transaction price, depending on how it is presented.
This distinction is especially important when comparing published market data with a final invoice. A published price may describe a standardized reference transaction. Your actual price may reflect volume, timing, credit terms, delivery conditions, and the availability of counterparties.
How does spot price differ from futures and forward prices?
Consider three prices for the same asset. The spot price applies to current or near-term delivery. The futures price applies to a standardized contract with delivery or settlement at a specified future date. The forward price applies to a privately negotiated agreement for future delivery.
A futures price is formed through trading in a standardized derivatives contract. The contract normally specifies the asset, quantity, quality, expiry, and settlement process. Futures can be used for hedging, speculation, or price discovery without requiring immediate ownership of the underlying asset.
A forward price is usually negotiated directly between counterparties. The parties can customize the quantity, delivery date, quality, and settlement terms. This flexibility can be useful, but it also introduces counterparty, liquidity, documentation, and valuation considerations.
The relationship between spot and futures prices is often described through the basis. In a simple formulation, the basis is the spot price minus the futures price. The basis can be positive or negative, and it changes as market expectations, carrying costs, and delivery conditions evolve.
When a futures contract approaches expiry, its price and the relevant spot price generally move toward one another. This process is known as convergence. It does not mean that every quoted spot price equals every futures price, because the contracts may reference different locations, grades, settlement methods, or delivery periods.
In EU carbon markets, the distinction is equally important. An EUA spot trade concerns an allowance available for current settlement, while an EUA future creates exposure to a specified later expiry. To examine the factors behind these differences, read our carbon market price discovery guide.
Why do spot prices change?
Spot prices change because buyers and sellers continuously reassess the value of immediate access to an asset. The most direct forces are supply, demand, liquidity, market expectations, and the cost of moving or holding the asset.
When immediate demand rises while available supply remains limited, buyers may compete for the asset and push the spot price higher. When supply increases or demand weakens, sellers may accept lower prices to complete transactions.
For commodities, the cost of carry can influence the relationship between spot and future prices. Cost of carry may include financing, storage, insurance, transport, deterioration, and security. These costs affect how much a market participant would pay to obtain the asset later instead of obtaining it now.
Energy markets provide a clear example. Weather can change demand for natural gas or electricity. Production outages can reduce supply. Inventory levels can influence expectations about future availability. Shipping constraints can create price differences between locations.
Financial assets respond to different forces. Currency spot rates react to interest-rate expectations, economic data, capital flows, and market sentiment. Equity prices reflect information about companies and wider markets. Carbon allowance prices can respond to industrial output, energy switching, regulatory changes, auction supply, and compliance demand.
Market structure also matters. A liquid market with many active buyers and sellers may update its spot price frequently. A less liquid market may rely on indicative quotes, assessed prices, or periodic transactions. In those settings, the published spot price may be a useful reference without representing a transaction completed at that exact moment.
Why is the final transaction price different from spot price?
The quoted spot price is often a starting point rather than the complete cost of a transaction. The final amount may include a market premium, brokerage fee, transport charge, financing cost, tax, insurance expense, storage cost, or settlement charge.
Physical precious metals illustrate this difference. A gold spot quote may represent the value of refined metal in a standardized market. A retail coin or bar can cost more because it includes fabrication, packaging, distribution, inventory, and dealer margin.
Industrial commodities can also trade above or below a benchmark. A buyer may pay more for a specific grade, urgent delivery, reliable supply, or a convenient location. A seller may accept less for material that requires additional testing, processing, or transportation.
The difference can also arise in carbon markets. An EUA benchmark may not equal the final price for a block trade, because the transaction can involve order size, execution method, credit arrangements, clearing, custody, and settlement terms.
For professional participants, transparency requires separating the benchmark from the complete economics of the transaction. A proper review should identify the quoted price, the spread, the fees, the delivery or settlement terms, and the costs that apply after execution.
How is a spot price used in market analysis?
Spot prices help businesses and traders understand the current value of an asset. They can support procurement decisions, inventory planning, hedging analysis, compliance management, valuation, and comparison with derivative prices.
The U.S. Bureau of Labor Statistics notes that spot prices are set in commodity markets and used in transactions involving raw materials and metals worldwide. Its BLS methodology also distinguishes spot prices from other price concepts used in economic measurement.
A procurement team may compare the current spot price with a budget or internal cost threshold. A trading desk may compare spot with futures prices to evaluate the curve, basis, or hedging opportunity. A compliance entity may monitor EUA spot prices when planning allowance purchases.
Spot prices can also act as inputs for derivatives valuation. Futures, forwards, options, and swaps derive part of their value from the underlying asset. Other variables may include time to expiry, volatility, interest rates, storage, convenience yield, and contractual settlement terms.
However, spot price alone does not answer every commercial question. It does not reveal whether an order can be executed at the displayed level. It may not include the cost of acquiring the desired quantity. It may also refer to an asset with different quality or delivery terms from the one you need.
For that reason, market analysis should treat spot price as one part of a broader decision framework. You should also review liquidity, execution conditions, counterparty exposure, settlement arrangements, and the total cost of ownership.
What should you check before using a spot price?
A spot quote becomes more useful when you understand exactly what it represents. Before relying on one, check the following points:
- Asset definition: confirm the commodity, security, currency, allowance, grade, or contract being quoted.
- Delivery terms: identify the location, settlement date, delivery window, and transfer mechanism.
- Quantity: check whether the quote applies to your order size or only to a standard market amount.
- Price type: distinguish a last traded price, bid, offer, midpoint, assessed benchmark, or executable quote.
- Additional costs: review spreads, commissions, storage, financing, transport, insurance, taxes, and custody charges.
- Market timing: confirm when the price was published and whether the relevant market is open.
- Risk controls: consider credit, settlement, margin, liquidity, and counterparty risks before execution.
For an EU ETS participant, this review may also include whether the platform supports both spot and derivatives trading, live market information, order controls, reporting, and settlement workflows. Our EU ETS trading price guide explains how market conditions and execution factors can affect the price you see.
Professional teams may also need shared access controls, position monitoring, API connectivity, and pre-trade limits. These features do not change the definition of spot price, but they can improve how efficiently a business observes and acts on that price.
Conclusion: use spot price as a reference, not the whole transaction
The spot price is the current or near-term market price for an asset intended for immediate delivery and settlement. It differs from futures and forward prices because those contracts establish terms for a later date. The most reliable interpretation considers the asset, location, quantity, liquidity, settlement convention, and additional costs. When you evaluate a quote, focus not only on the displayed number but also on whether it is executable and what the completed transaction will cost.
Take action with Initiativ
Understanding spot price is useful, but professional carbon trading also requires reliable execution, market visibility, risk controls, and post-trade processes. If your organization manages EU ETS exposure, procurement, or trading activity, you need infrastructure that connects pricing decisions with operational execution.
We provide access to EU Allowances in spot and derivatives form, together with live price monitoring, configurable alerts, pre-trade risk controls, API connectivity, order-book access, position management, reporting, confirmation, and settlement workflows. Explore carbon trading for traders and corporates to assess how our platform can support your professional market activity.
Frequently Asked Questions
What is the simplest definition of spot price?
The spot price is the current market price for buying or selling an asset with immediate or near-term delivery and settlement. It is also known as the cash price.
Is the spot price the same as the final price I pay?
Not always. The final price may include premiums, commissions, transport, storage, financing, insurance, taxes, custody, or other transaction costs.
What is the difference between spot and futures prices?
A spot price applies to current or near-term delivery, while a futures price belongs to a standardized contract for a specified future date. Their relationship can be influenced by financing, storage, supply, demand, and market expectations.
What is the difference between a spot price and a forward price?
A spot price concerns the current market transaction, while a forward price is negotiated today for delivery or settlement later. Forward agreements are generally customizable, whereas futures contracts are standardized.
Can businesses trade EUA spot prices?
Eligible professional participants can use EUA spot markets for compliance procurement, trading, and position management. Initiativ supports professional access to EUA spot and derivatives markets, subject to onboarding and applicable qualification requirements.

Let’s connect
Do you want more information about what we do?